- Home
- US Small Business Tax Compliance
- Self-Employment Income
- Small Business Deduction
New 20% Small Business Deduction
US Tax Reform 2018
by L. Kenway BComm CPB Retired
This is the year you get all your ducks in a row!
Updated October 30, 2026
(based on an AdminBooks webinar with permission from Renee Daggett)
What's New OBBBA Changes to the QBI Deduction
The One Big Beautiful Bill Act (OBBBA), signed July 4, 2025, made the 20% Qualified Business Income (QBI) deduction permanent. It was originally scheduled to expire after 2025 under the 2017 Tax Cuts and Jobs Act.
2026 Income Thresholds and Phase-in Ranges
The income thresholds and phase-in ranges are adjusted annually for inflation. For the 2026 tax year, the amounts are:
| Filing Status | Threshold | End of Phase-in Range |
|---|---|---|
| Married filing jointly | $403,500 | $553,500 |
| Married filing separately | $201,775 | $276,775 |
| All other filing statuses | $201,750 | $276,750 |
These amounts are based on taxable income before the QBI deduction.
The OBBBA also expanded the phase-in ranges. They increased from $100,000 to $150,000 for joint filers and from $50,000 to $75,000 for other filing statuses.
New Minimum Deduction Beginning in 2026
Eligible taxpayers may receive a minimum QBI deduction of $400 if they have at least $1,000 in combined qualified business income from one or more active businesses in which they materially participate.
Annual Updates
The income thresholds and phase-in ranges change annually with inflation. This box will be updated as new amounts are announced by the IRS.
Here is a brief summary of a webinar I attended on the 20% small business deduction.
AdminBooks hosted three free webinars in July and August of 2018 to help educate and navigate the new tax laws and how they may impact your situation. None of the information presented in any of their webinars is to be construed as specific advice for your individual situation. It is presented for educational purposes only. Please contact AdminBooks if you wish advice pertaining to your specific situation.
A note about the numbers: The income thresholds and eligibility limits discussed in the original webinar reflect the 2018 tax rules. For current thresholds and limits, see the What's New box above.
 AdminBooks
Renee Daggett EA is the President of AdminBooks and the author of "Your Financial Flight Plan: Pilot Your Business to Profitability". Based in California, the AdminBooks team helps small businesses be responsive to complex and specialized issues that affect your business such as changes to tax law, software, compliance or employment laws.
Chat Continues Below Advertisement
Who qualifies for the 20% small business deduction?
- Sole proprietorships (Schedule C)
- Real estate investors (Schedule E)
- Disregarded entities (single member LLCs - Schedule C)
- Multi-member LLCs and partnerships (Form 1065)
- any entity taxed as an S corporation
C Corporations do not qualify.
What is the Small Business Deduction?
The qualified small business income deduction is a deduction from taxable income, not Adjusted Gross Income (AGI). It allows eligible taxpayers to deduct up to 20% of their Qualified Business Income (QBI). Special rules apply to specified service trades or businesses (SSTBs).
QBI is defined as business income minus expenses ... i.e profit. For clarity, QBI is generally the net profit from a qualified business after certain business-related deductions.
QBI does not include capital gains, dividend/interest income, employee wages, owner/partner draws (which are not business expenses), money generated outside the U.S.. This list is not exhaustive.
LIMITATIONS - Specified Service, Wage and Property
Specified service trades or businesses (SSTBs) are subject to special rules. These include businesses in fields such as health, law, accounting, actuarial science, performing arts, consulting and financial services. Whether an SSTB qualifies for the deduction depends on the taxpayer's taxable income.
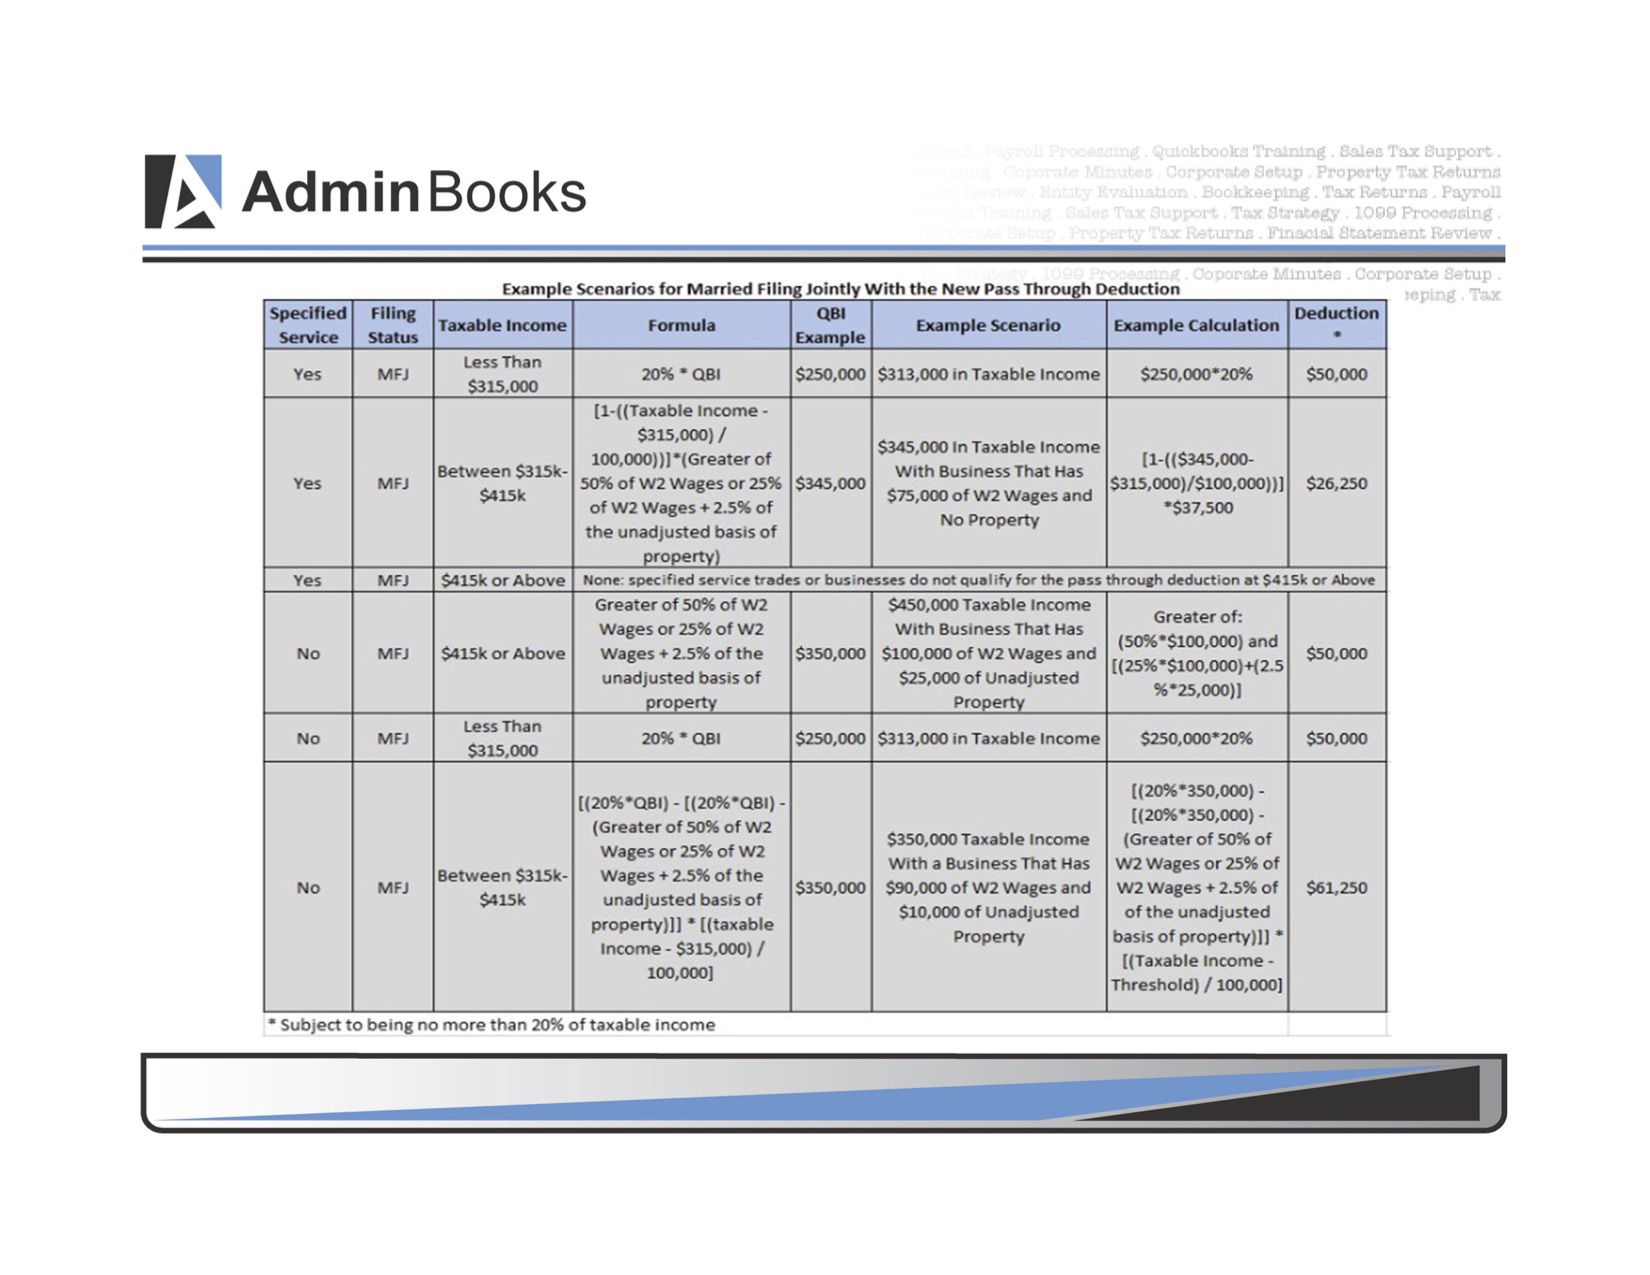
There is no deduction unless taxable income is below certain thresholds. This means that if 2018 taxable income is over $415,000 ($207,500 for non-MFJ*), no deduction is available. See the AdminBooks slide below for the thresholds.
*MFJ = married filing jointly
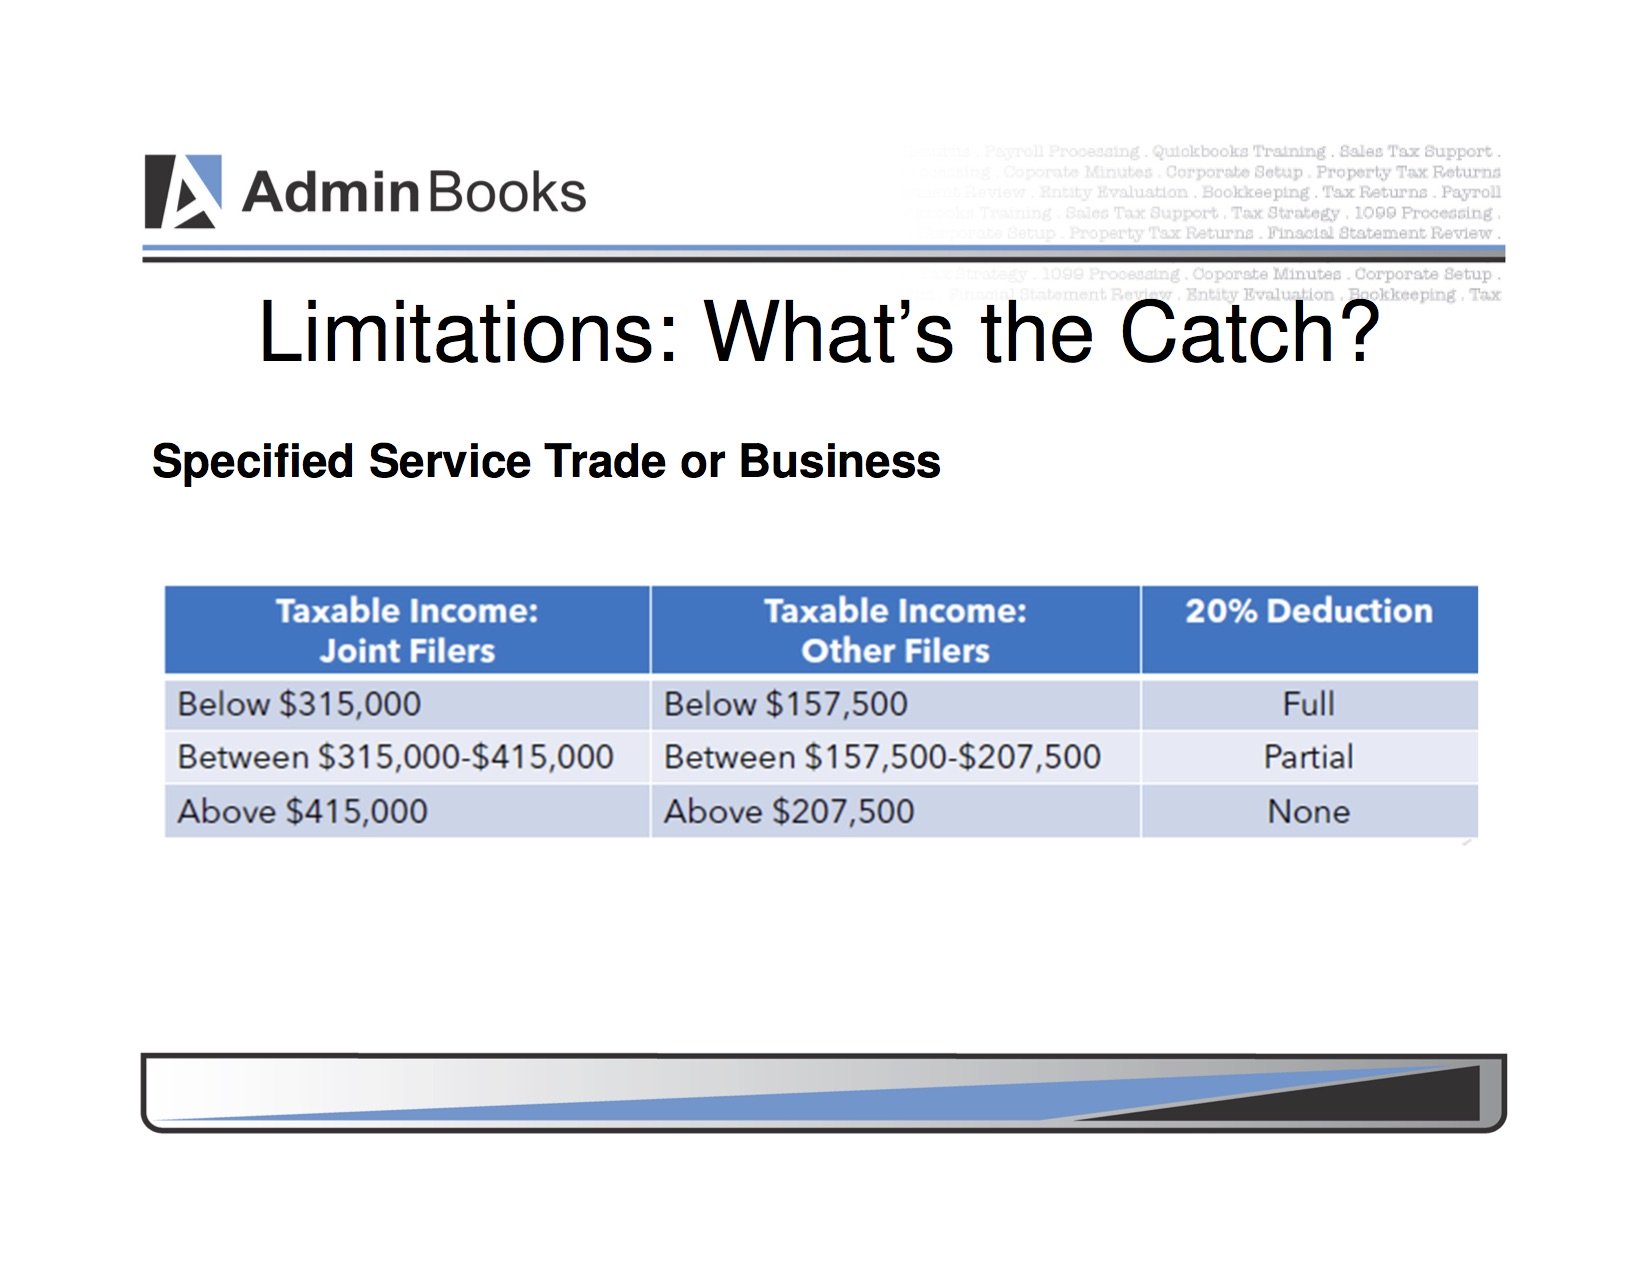 These are the original 2018 thresholds.
For current income thresholds and phase-in ranges, see the What's New box at the top of this article.
There are also wage and property limitations which are as follows:
The qualified small business income deduction is limited to the greater of:
(a) 50% of W-2 wages paid by business; or
(b) 25% of W-2 wages plus 2.5% of taxpayer's share of basis of "qualified business property"
... BUT it only applies at certain taxable income levels. Three general situations possible are (1) have no wages but hold property, (2) have wages but no property, or (3) have wages and property.
See the AdminBooks summary slide below. Renee and her team can help you determine if it makes sense to change your entity structure ... or if you should convert 1099 contractors to W-2 employees. It is not a given as bumping up wages might increase your deduction but it may not be offset by the higher payroll taxes.
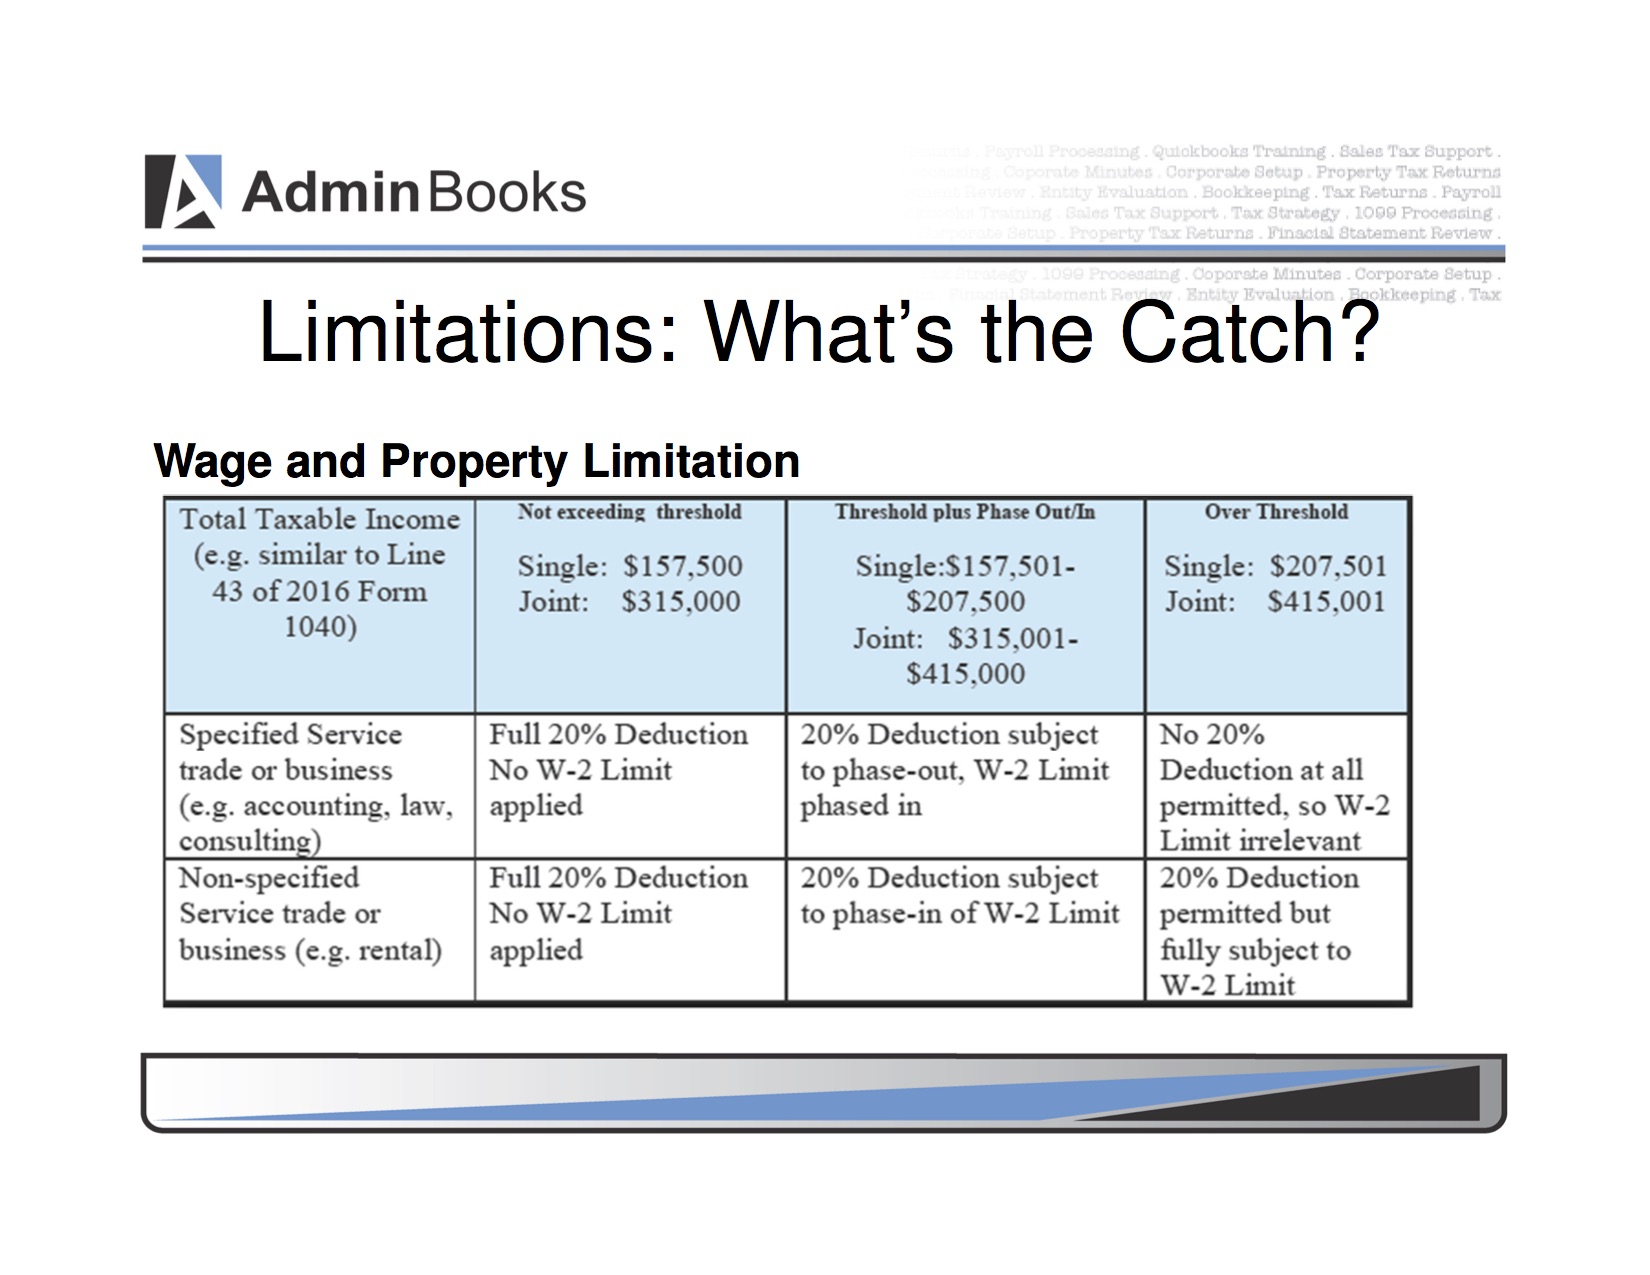
You can ignore the limitations if your taxable income is below $315,000 / $157,500 as you are eligible for the full deduction. AdminBooks can also help you strategize ways to keep your taxable income below the thresholds.
Keep in mind ... you must still calculate your self-employment taxes on net business income BEFORE the 20% small business deduction.
Chat Continues Below Advertisement
Calculation Steps
- Identify your QBI for EACH activity.
- Compute the initial 20% deduction for EACH activity.
- Apply wage and property limitations for EACH activity to compute a tentative deduction.
- Combine the tentative deduction from EACH activity.
- Limit your overall deduction to taxable income less net capital gains.
A FlowChart is Worth a Thousand Words
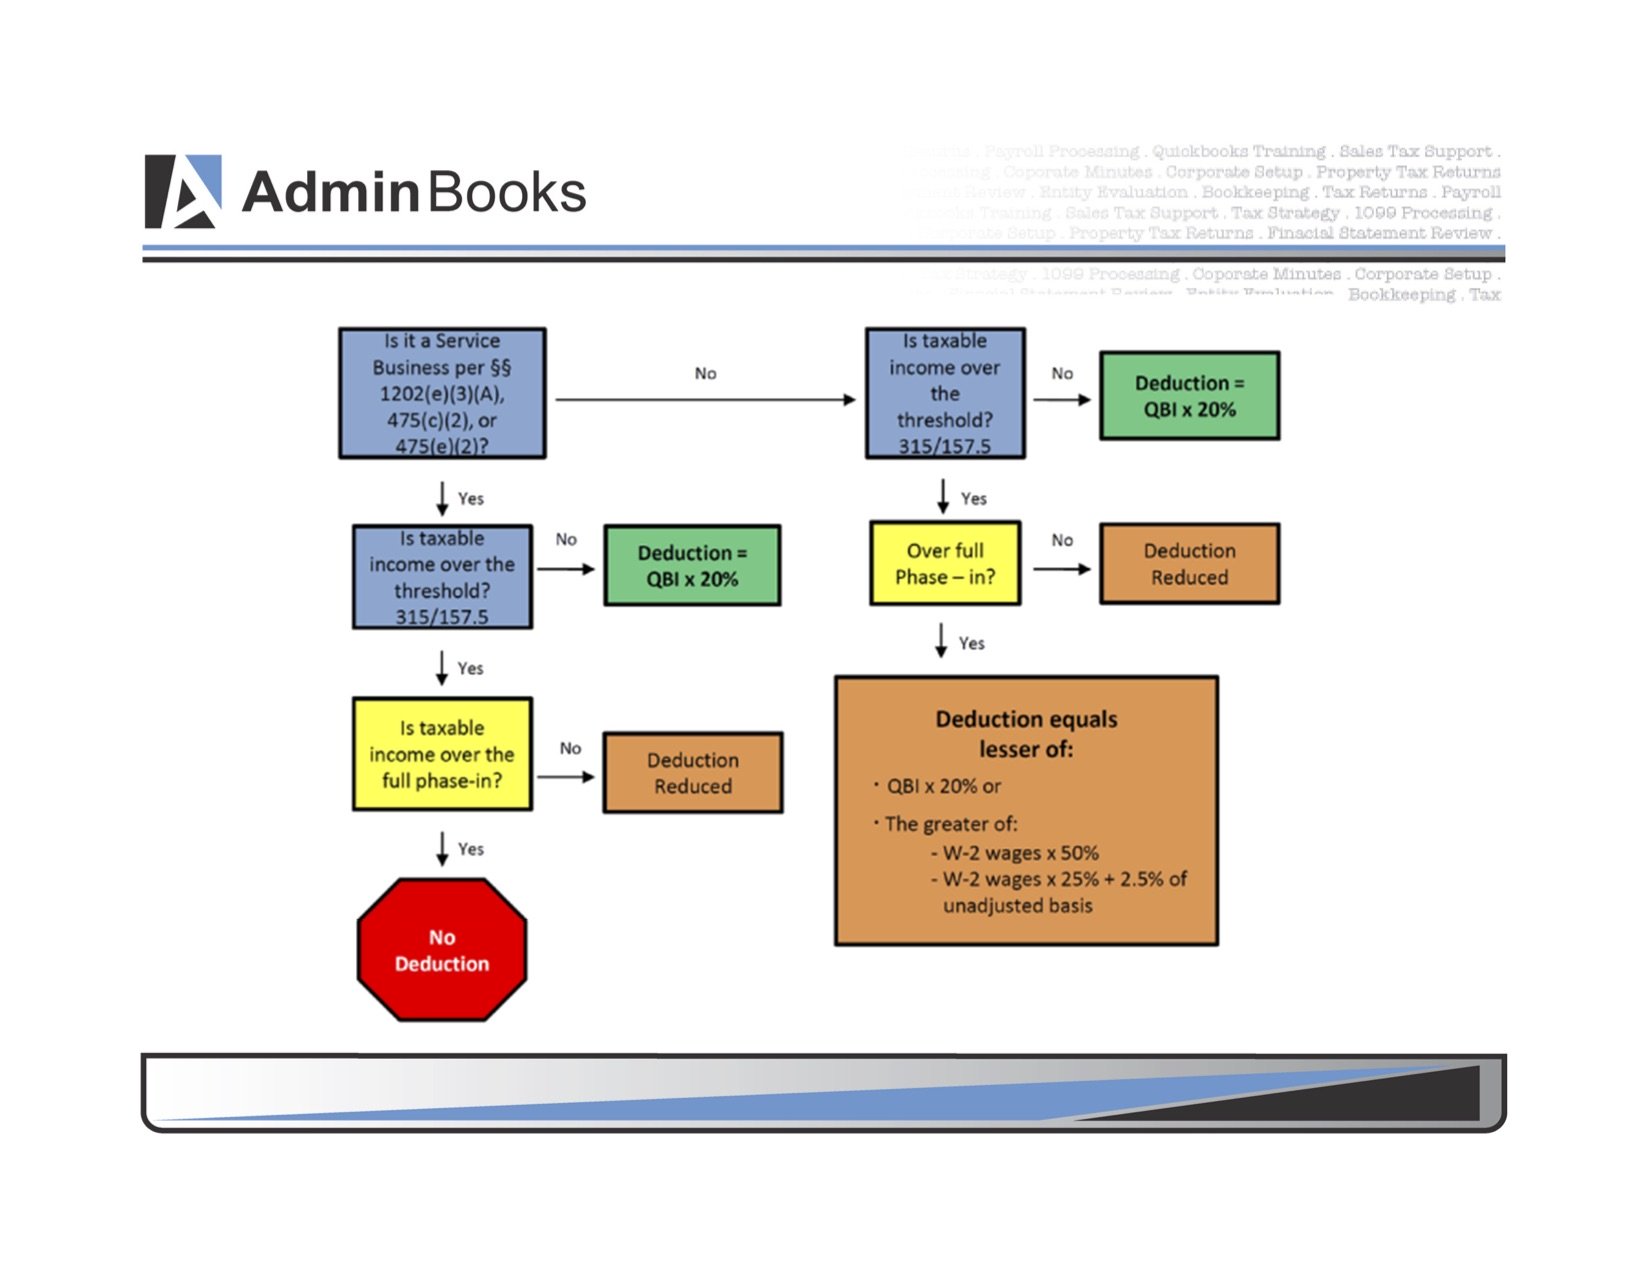
And finally, here is a great overview depicting various scenarios with the small business deduction.
It's been great chatting with you.
Your Tutor
Home › U.S. Self-Employment Income › 2018 Tax Reform - Small Business Deduction